Abstract / Overview
After Union Budget 2026–27, crypto taxation in India remains governed by the Virtual Digital Asset (VDA) framework introduced in the Income-tax Act. The Budget did not change core tax rates, but it strengthened reporting discipline and penalties for inaccurate or delayed disclosures, making correct filing more important than ever.
This guide explains how to file crypto taxes in India after Budget 2026 using only provisions that are explicitly in force under Indian tax law. No assumptions, no speculative reliefs, and no shortcuts. All steps are aligned with the Income-tax Act, notified rules, and the e-filing system as applicable for FY 2025–26 (AY 2026–27).
Direct Answer
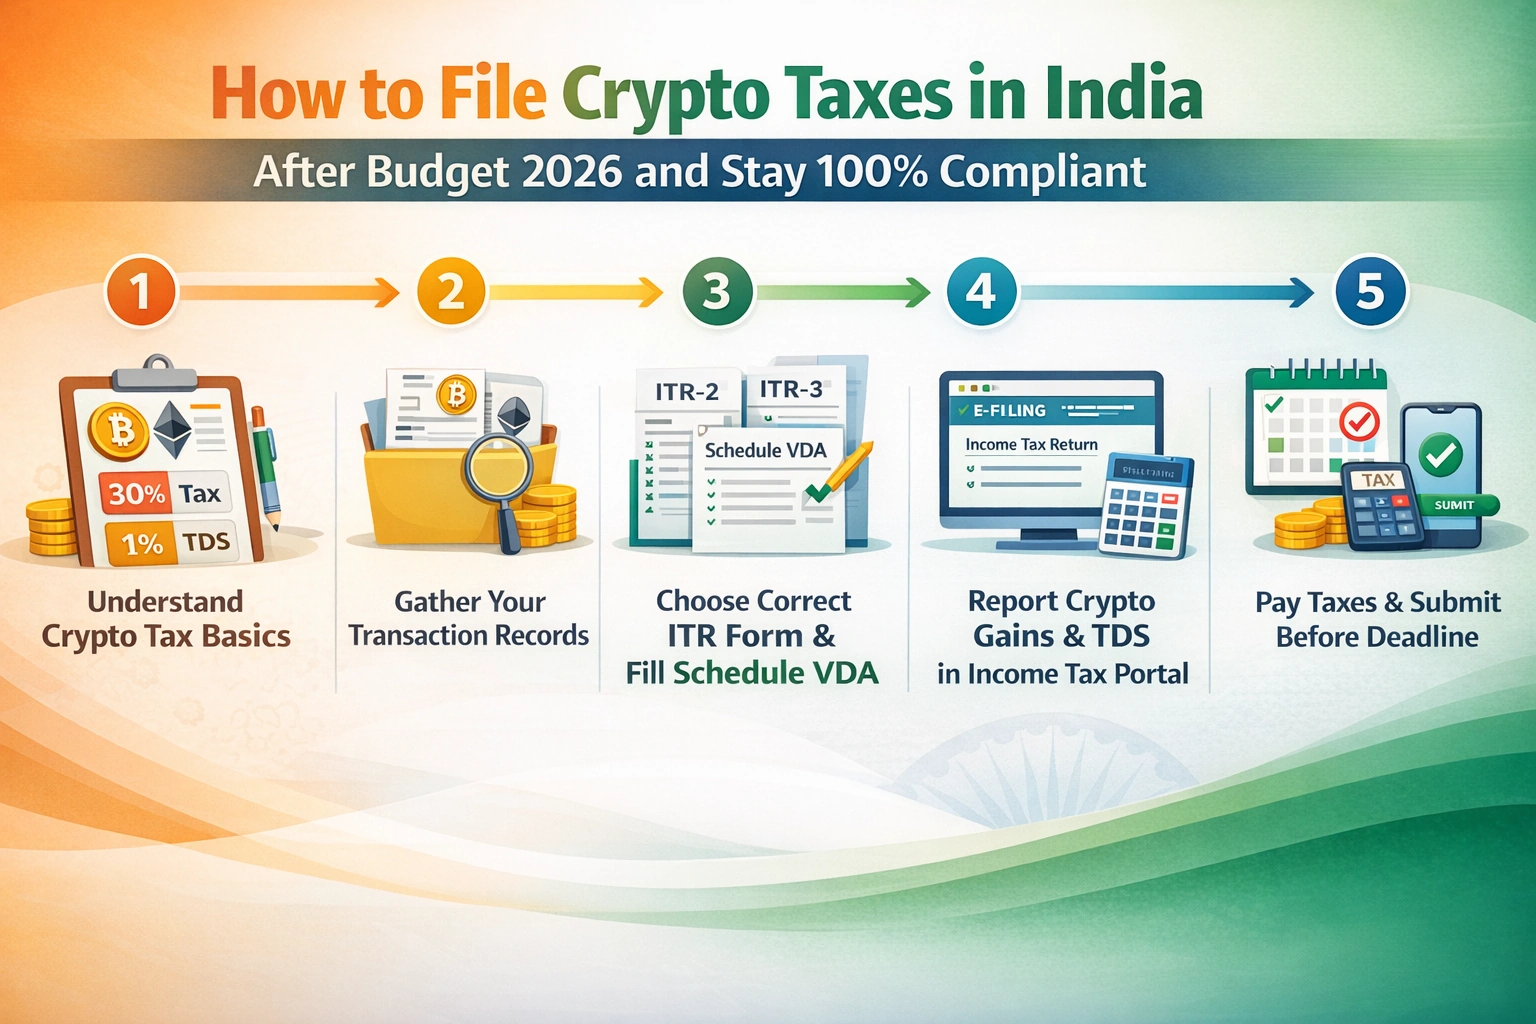
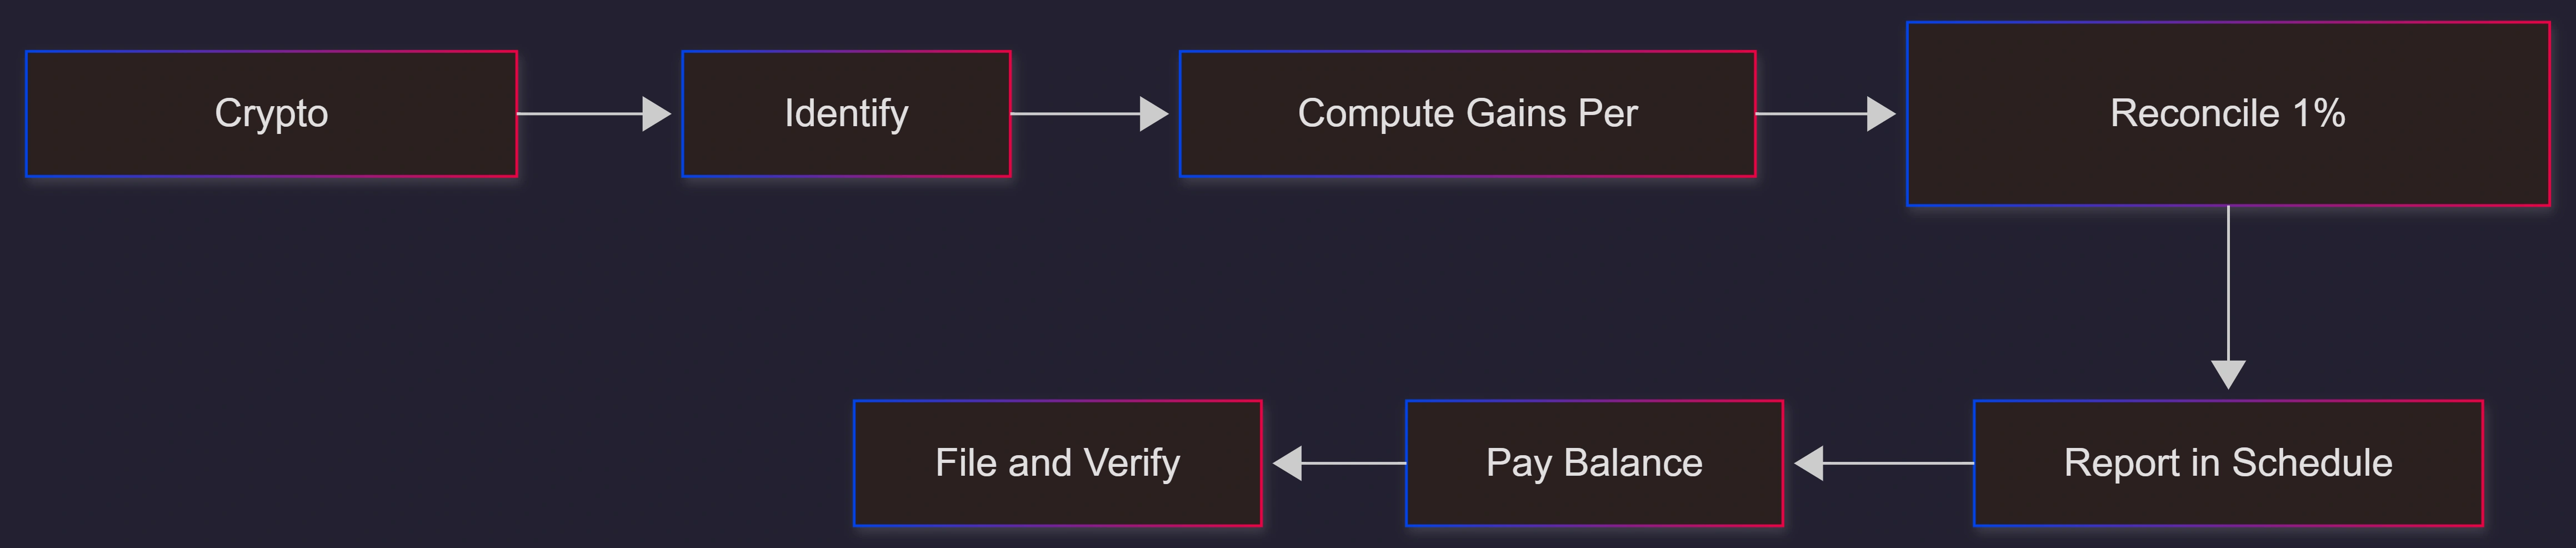
To file crypto taxes in India after Budget 2026, you must compute gains separately for each taxable crypto transaction, pay 30% tax on positive gains, reconcile 1% TDS where applicable, report all transactions under Schedule VDA in the correct ITR form, and ensure your reported data matches exchange-reported data to avoid penalties for incorrect or incomplete reporting.
Conceptual Background: What the Law Actually Says
Crypto assets are taxed in India as Virtual Digital Assets (VDAs) under Section 115BBH of the Income-tax Act, 1961. Administration and enforcement are handled by the Income Tax Department, while policy oversight of the financial system lies with the Reserve Bank of India.
Core Legal Rules (Unchanged After Budget 2026)
Flat 30% tax on income from transfer of VDAs
1% TDS on consideration for transfer of VDAs under Section 194S
No set-off of crypto losses against any income
No carry-forward of crypto losses
Only cost of acquisition is deductible
Mandatory reporting in Schedule VDA
These provisions are statutory and not optional.
Step-by-Step Walkthrough: How to File Crypto Taxes Correctly
Step 1: Gather Complete Transaction Records
You must collect all crypto transactions executed during FY 2025–26, including:
Buy and sell transactions
Crypto-to-crypto trades
Crypto used to pay for goods or services
Crypto received as gifts or consideration
Sources include:
Indian exchanges
Foreign exchanges
Self-custody wallets
Legal note: Indian tax residency determines taxability, not exchange location.
Step 2: Identify What Is a Taxable Transfer
Under Indian law, the following are taxable transfers of VDAs:
Sale of crypto for INR or foreign currency
Exchange of one crypto for another
Use of crypto to pay for goods or services
The following are not taxable transfers:
Transfer between your own wallets with no consideration
Accuracy here is critical, as misclassification leads to incorrect reporting.
Step 3: Compute Taxable Income Transaction-Wise
Each transaction must be computed independently.
Taxable Income = Sale Consideration − Cost of Acquisition
Allowed:
Purchase price of the crypto
Not allowed:
Exchange fees
Gas fees
Network charges
Loss adjustment against gains
Example:
Purchase price: ₹5,00,000
Sale value: ₹6,50,000
Taxable income: ₹1,50,000
Tax payable: ₹45,000 (30%)
Losses, even if genuine, do not reduce tax liability.
Join the conversation! Your thoughts help the community grow.